


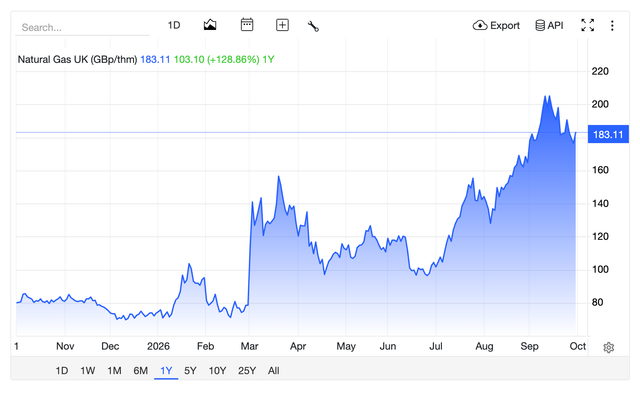
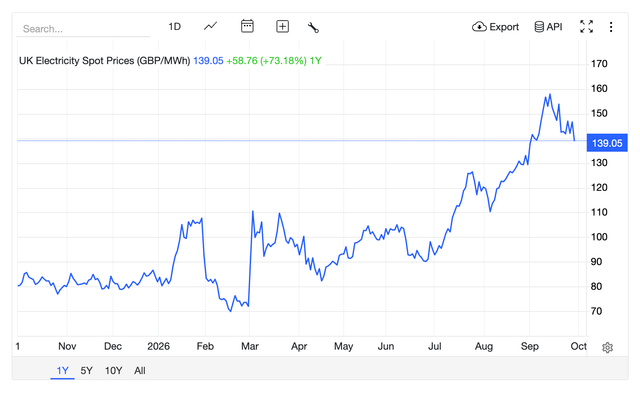
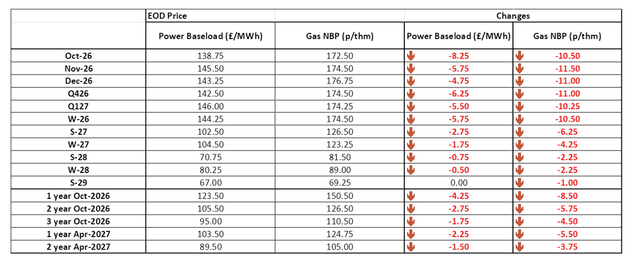
Wholesale gas and electricity prices dropped on Tuesday, which was welcome news, with gas drops being in double digits.
To put that into context, prices are now broadly at the same level as they were on 7 September and around 20% higher than they were on 3 August for one- and two-year contracts.
The geopolitical situation is extremely uncertain, and we have no visibility of when it will improve at the moment. The movements in the wholesale market appear to be driven by operators in the Middle East finding alternative ways to transport commodities. Gas prices remain far more volatile than electricity prices because Qatar is still having difficulties exporting any sizeable volumes of LNG.
| Gas: Gas prices fell off yesterday. Front month and front season contracts fell around 6%. Once again, the main price driver is geopolitics, with the US and Iran committing to “more serious” talks to look at ending the conflict between them. Bearish weather fundamentals in the prompt further pressured price. This morning the market has opened similar to last night’s close. Power: Power contracts also shed value yesterday shadowing bearish NBP movements. Upwards revisions to next week’s wind output pressured the front week contract, with losses of around 10%. The market has opened slowly this morning, with little change versus last night’s settlement. Oil: After early gains, prices reversed yesterday, settling lower. Crude closed the day at around $96/bbl. Carbon (EUAs): The ICE Dec-26 closed at €85.95/t last night. The contract opened this morning at €85.98/t. Carbon (UKAs): The ICE Dec-26 traded to £61.86/t yesterday. At time of writing the contract has yet to trade. |
#gas #electricity #businessutilities #businessgas #businesselectricity